You may have heard of a new savings initiative that aims to strengthen the financial future of the next generation. The Trump Savings Account, launched on July 4, 2026, gives families a new way to help children build long-term wealth with no earned income requirement and no impact on other retirement savings limits. While some program details are still being finalized, the framework already offers valuable insight into how families may benefit.
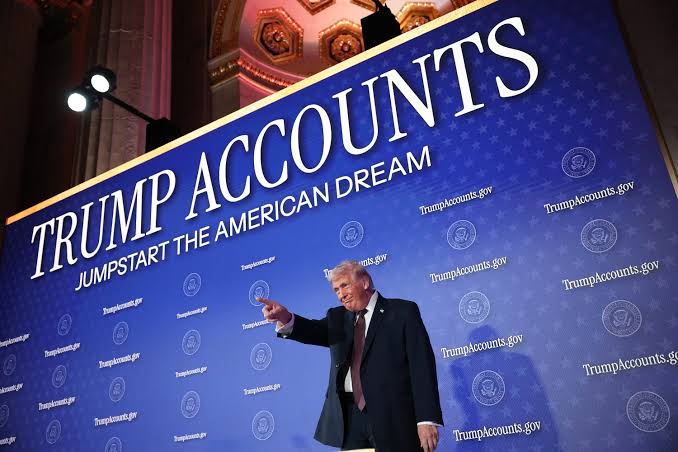
What Is the Trump Savings Account?
As of July 4, 2026, families are eligible to open a Trump Savings Account for a child and begin contributing. The purpose of the program is simple: to help children start adulthood with meaningful financial resources. Funds in the account must be invested in approved mutual funds or ETFs that track major market indexes, allowing savings to grow over time.
The child is both owner and beneficiary, giving them full control once they reach adulthood. Although specifics such as the account provider and administrative details are still to be announced, the general structure and tax treatment of the account have been outlined.
Already Applied for A Trump Account?
Trump Accounts became available for contributions on July 4, 2026, but the paperwork behind them started well before that. Parents were able to file IRS Form 4547 with their 2025 tax return (due April 15, 2026) to open a Trump Account for an eligible child and elect the one-time $1,000 Treasury contribution, and many did. As of the IRS’s most recent update, roughly 4 million children had been signed up, with about 1 million already claiming the $1,000 contribution.
If you filed your taxes without including the form, you’re not out of luck: you can still mail a standalone Form 4547 to the IRS, or, as of late May 2026, submit it electronically and check its status directly through your IRS Individual Account online. Since enrollment numbers still outpace confirmed eligibility for the government deposit, it’s worth logging in to check where your child’s account actually stands.
Who Is Eligible?
Any child with a Social Security Number who does not turn 18 during the calendar year can have an account. To receive contributions each year, the beneficiary must remain 17 or younger for the entire year.
In addition, the federal government will make a one-time $1,000 deposit for newborns born between January 1, 2025, and December 31, 2028, automatically giving many children an early head start.
Download the Trump Accounts App
Keep an eye on your child’s future right from your phone. With the Trump Accounts app, you can track your child’s tax-advantaged investment account, see their balance grow, and check their estimated value at 18, all in one place.
Every eligible child born between 2025 and 2028 starts with a $1,000 contribution from the U.S. Treasury, with funds invested in American companies and growth potential boosted by supporters like Dell, Uber, Visa, SoFi, Chime, Chipotle, and others. The account is fully in your child’s name until they turn 18, when it’s theirs to use for education, a home, or anything else, with the same tax advantages as a traditional IRA.
Key Benefits for Families
One of the most attractive features is that children are not required to have earned income. Contributions also do not reduce or interfere with IRA or 401(k) limits. That means a teenager with a part-time job could still fully fund a Roth or traditional IRA while receiving contributions to their Trump Savings Account.
Parents may contribute up to $5,000 per year after taxes, and contributions can be made by almost anyone—relatives, friends, nonprofits, and even employers. Employers may contribute up to $2,500 tax-free, though families should note that a child cannot receive both the full $5,000 parental contribution and the $2,500 employer contribution in the same year.
How Taxation Works
Withdrawals are not allowed before age 18. Once a child reaches adulthood, the account will convert automatically into an IRA, and standard IRA withdrawal rules will apply.
Tax treatment depends on the type of contribution:
- After-tax contributions from parents or individuals become the account’s basis and are not taxed when withdrawn.
- Government deposits, employer contributions, charitable gifts, and all investment earnings are taxable upon withdrawal.
- When funds are taken out, withdrawals are prorated between taxable and tax-free amounts based on the account’s overall composition.
Withdrawals before age 59½ may also face a 10% early distribution penalty unless an exception applies.
Planning for the Future
This new program has the potential to become a powerful savings tool for education, a first home, or long-term financial planning. Families can begin considering how the Trump Savings Account may fit into their broader financial strategy.
If you’d like guidance on how this account could benefit your children or how to prepare for upcoming changes, contact NSO and Company at (317)-588-3131. Our team is here to answer questions, review your options, and help you build a plan that supports you and your family’s financial future.
Frequently Asked Questions
Our clients appreciate our fair, transparent pricing — no surprise fees, no confusing invoices. Individual tax returns start at $750, and business returns start at $1,500. If you’d like to talk through your specific situation before committing, a one-hour consultation with a CPA and tax preparer is $250.
Every client’s needs are different, so these starting rates can vary based on the complexity of your return or the scope of services you need. Visit our pricing page for more detail.
If you need accounting, bookkeeping, or tax services, contact us today — we’d love to learn more about your situation and provide pricing tailored to your needs.
We work with a wide variety of individual and business clients across central Indiana. Our clients range from entrepreneurs and small business owners to business professionals, retired individuals, families, and business corporations of all sizes.
Whether you’re just starting a business, managing personal and family finances, planning for retirement, or running an established company, we tailor our accounting, tax, and advisory services to fit where you are and where you’re headed. No two clients are exactly alike, and neither is our approach — we take the time to understand your specific situation so we can offer advice that actually applies to you.
NSO and Company is located in Fishers, Indiana, just off I-69 near the intersection of Lantern Road and 96th Street — an easy, convenient drive from anywhere in the Indianapolis area. Our office is at 8950 Fitness Lane, Suite 100, Fishers, IN 46037.
We’re open Monday through Friday, 8 am – 4 pm, and welcome walk-ins as well as scheduled appointments. If you’d like to speak with someone directly, call us at 317-588-3131.
NSO and Company combines years of experience with personalized service to help individuals and businesses prepare their taxes accurately and on time. We take the time to understand your situation, answer your questions, and look for opportunities to help you maximize your tax savings, while staying compliant and making the process as smooth as possible. Our clients also value our fair pricing and the confidence that comes from working with a trusted local firm.